The desperate gamble: how Niger’s junta is risking everything with a 5 billion dollar demand
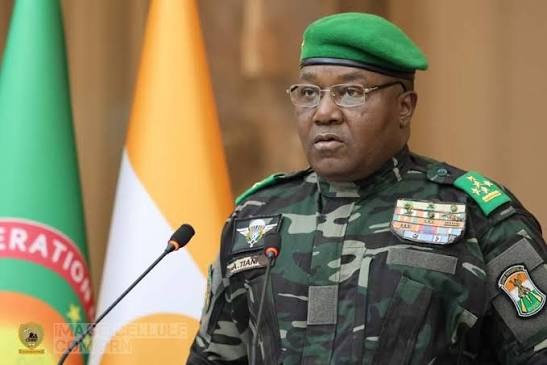
The military-led government in Niger, led by General Abdourahamane Tiani, faces a growing financial crisis as it resorts to increasingly aggressive measures to fill its empty coffers. In a move that has stunned international partners and industry observers alike, the transitional authorities have issued a staggering ultimatum to the China National Petroleum Corporation (CNPC) and its subsidiaries, WAPCO and SORAZ: deliver over $5 billion in francs CFA within 45 days or face severe penalties.
This audacious demand comes on the heels of a dramatic deterioration in Niger’s economic situation, exacerbated by sharp budget cuts, declining state revenue, and unsustainable military spending. With public finances in freefall and no clear path to recovery in sight, the military regime appears willing to take extreme measures to address its fiscal emergency.
From financial crisis to financial extortion
The junta’s justification for this drastic step is rooted in accusations that CNPC has failed to repatriate sufficient export revenues from the Agadem oil block. According to official statements, only 105 billion francs CFA—about $175 million—have returned to Niger over the past two years. However, critics argue that this narrative conveniently ignores the complex financial arrangements in place, including a $400 million loan from Beijing in 2024, to be repaid directly from oil revenues.
The sudden imposition of this ultimatum has raised serious concerns among economic analysts, who warn that such aggressive tactics could backfire spectacularly. With Niger already struggling to attract foreign investment and facing widespread international condemnation for its democratic backsliding, this move risks further isolating the country and accelerating capital flight.
The seven crushing demands that reveal a broader strategy
Behind the headline-grabbing financial demand lies a set of seven punitive conditions designed to exert complete control over CNPC’s operations in Niger. Each of these demands not only challenges the integrity of the existing agreements but also sets a dangerous precedent for future business dealings in the country.
Breaking down the ultimatum’s demands
- Liquidity injection mandate: CNPC must repatriate enormous sums in francs CFA on an unrealistic schedule, effectively draining the company’s reserves.
- Mandated localization policies: The regime insists on imposing local hiring quotas—up to 90%—despite the lack of technical expertise within Niger’s workforce.
- Pipeline interference: The junta seeks to renegotiate the terms of the Niger-Benin pipeline, valued at $2.3 billion, by overturning existing audits and imposing unilateral tariff revisions.
- Refinery takeover: The military government intends to seize control of the SORAZ refinery’s governance by gradually replacing Chinese executives with local appointees.
- Reserve revaluation: Niamey demands an independent reassessment of the Agadem oil fields to inflate its tax share through renegotiated terms.
- Forced reinvestment: The CNPC is pressured into injecting an additional $1 billion into exploration projects such as Dinga Deep and Abolo-Yogou regardless of market conditions.
- Administrative infiltration: The junta seeks to place government-appointed officials within CNPC’s decision-making bodies to oversee every operational move.
A pattern of intimidation and financial bullying
This latest ultimatum is not an isolated incident but the culmination of a broader campaign of intimidation against CNPC. Since early 2025, the regime has escalated its hostilities through the rapid expulsion of Chinese executives, repeated financial coercion, and the creation of pressure commissions designed to cripple the company’s operations.
The military government’s aggressive posture reflects its growing desperation as domestic and international criticism intensifies. With declining foreign reserves, restricted access to global capital markets, and mounting public unrest over economic hardship, the regime appears willing to risk long-term damage to foreign relations in pursuit of short-term financial relief.
The potential fallout: economic collapse or foreign investor exodus
As the 45-day deadline looms, the consequences of Niger’s financial gamble are becoming increasingly clear. Economic analysts warn that if the demands are not met, CNPC could pull out entirely, taking billions in future investments with it. This would leave Niger’s already fragile economy in even greater peril, cutting off not only oil revenues but also access to critical infrastructure funding and technical expertise.
The regime’s heavy-handed tactics also send a chilling message to other foreign investors operating in Niger. If the government can so brazenly target one of its largest investors, what prevents it from turning on others? The resulting erosion of investor confidence could trigger a mass exodus of foreign capital, further destabilizing an economy already teetering on the brink of collapse.
Is there a way out of this self-inflicted crisis?
With no immediate signs of relief and international pressure mounting, Niger’s military leaders face a stark choice: abandon their aggressive demands and seek alternative financial solutions, or double down on their extortionist tactics and risk total economic isolation.
As the clock ticks down on the ultimatum, the world watches closely to see whether Niamey will backtrack from its extreme demands or embrace further confrontation. One thing is certain: the fallout from this gamble will reverberate throughout Niger’s economy for years to come, shaping the country’s financial future regardless of the outcome.